

UK DIY News
Kingfisher Upgrades Guidance; Standout Performance From Screwfix
Kingfisher plc has published half year results for the six months ended 31 July 2026 (unaudited).
H1 26/27 Highlights
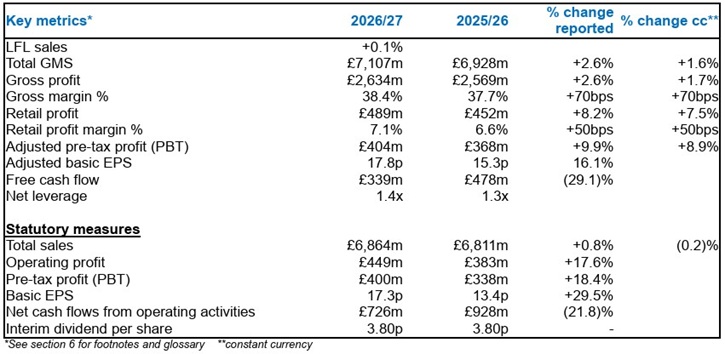
- Total sales including marketplace GMS* +1.6%. Underlying* LFL sales +0.3% driven by higher customer transactions. Statutory sales +0.8%(1)
- Standout performance from Screwfix with LFL +5.6% - Market share gains(2) at Screwfix, Poland and Spain. Castorama France and B&Q held share. Brico Dépôt France performance impacted by heatwaves due to category mix
- Strong momentum across trade, e-commerce and marketplace
- Trade sales growth* +16% ex-Screwfix. Group trade sales penetration* increased to 31% (+3pts)
- E-commerce sales* growth +16% ex-Screwfix. Group e-commerce penetration* reached 22% (+2pts)
- Marketplace GMV* up +42% to £372m, with profit contribution(3) £13.4m (H1 25/26: £7m) - Adjusted PBT +9.9%(1) to £404m, driven by gross margin expansion +70bps, disciplined cost control and a £14m one-off business rates refund. Statutory PBT +18.4% to £400m
- Adjusted EPS up +16.1% to 17.8p(1), supported by profit growth and share buybacks
- £339m free cash flow delivered
- Announcing interim dividend of 3.8p
Upgrading FY 26/27 Guidance(4)
- Adjusted PBT of £595m–£635m (previously £565m–£625m) and free cash flow of £480m–£520m (previously £450m–£510m)
- £300m share buyback ongoing, £125m purchased to date, commencing third tranche of £50m this week
Thierry Garnier, Chief Executive Officer, said: “We delivered a solid H1 performance, growing sales, gross margin and profits through market share gains and continued momentum across trade, e-commerce, marketplace and group sourcing. We are building a stronger, more resilient Kingfisher, with our strategic priorities creating new growth opportunities and strong financial discipline supporting performance across the business. While the consumer environment remains mixed, our consistent delivery, strategic progress and opportunities ahead give us the confidence to upgrade our guidance.”
Note: All commentary below is in constant currency unless otherwise stated.
Financial highlights
Sales
- Total sales including marketplace GMS +1.6% driven by continued momentum in strategic growth drivers
- Strong growth at Screwfix, Poland and Iberia, driven by trade, and e-commerce initiatives, product innovation and seasonal categories, partly offset by lower sales at B&Q and Brico Dépôt France
- Market share gains* at Screwfix, TradePoint, Castorama Poland and Spain. Castorama France returned to growth in Q2 and performed broadly in line with its market in the half. B&Q broadly in line with the market. Brico Dépôt France impacted by heatwaves due to category mix
- LFL sales growth of +0.1% and +0.8% space growth, partly offset by (0.2)% impact from converting two Castorama France stores to franchises
Gross margin and cost
- Gross margin expansion of +70 basis points to 38.4%, driven by Kingfisher’s buying and sourcing scale, growth from marketplace, retail media, FX tailwinds and the sale of Romania, partly offset by headwinds from freight and a growing share of trade
- Operating costs increased +0.4%, reflecting the impact of new store openings and higher staff pay rates including two months of increased UK employer National Insurance contributions. These increases were partly offset by structural cost reductions and a £14m one-off business rates refund in the UK
Pre-tax profit
- Adjusted PBT +9.9%(1) growth to £404m driven by gross margin expansion of +70bps and disciplined cost control. Excluding the one-off £14m UK business rates refund, adjusted PBT increased +6.1%
- Retail profit +7.5% to £489m(1), with retail profit margin of 7.1% +50bps
- Statutory PBT +18.4% to £400m (H1 25/26: £338m), with the prior year including a £31m loss related to the disposal of Romania included in adjusting items
- Adjusted EPS +16.1% to 17.8p(1), reflecting profit growth and the ongoing share buyback programme. Statutory basic EPS was up +29.5% to 17.3p
Free cash flow
- £339m free cash flow delivered, underpinned by 2 days stock improvement
- Gross capital expenditure of £171m, reflecting investment in new stores, new ranges to support growth, technology and store maintenance
- Interim dividend maintained at 3.8 pence per share
FY 26/27 guidance(4)
- Adjusted PBT in the range of approximately £595m–£635m (previously £565m–£625m)
- Free cash flow in the range of approximately £480–£520m (previously £450m–£510m)
Key assumptions
- Space: sales impact of c.+1%, mainly from Screwfix UK & Ireland, B&Q and Castorama Poland
- Net finance costs: c.£105m (FY 25/26: £91m) • Adjusted effective tax rate: c.26% (FY 25/26: 26%)
- Capex: c.£400m (FY 25/26: £388m)
- £13m non-recurring 2025/26 losses(5)
Share buyback
In line with our capital allocation policy, in March 2026 the Board determined that a further £300m of surplus capital was available to return to shareholders via a share buyback programme. Two tranches totalling £125m have been completed. The third tranche of £50m is commencing this week and expected to be completed by December.
Trading Review by Division
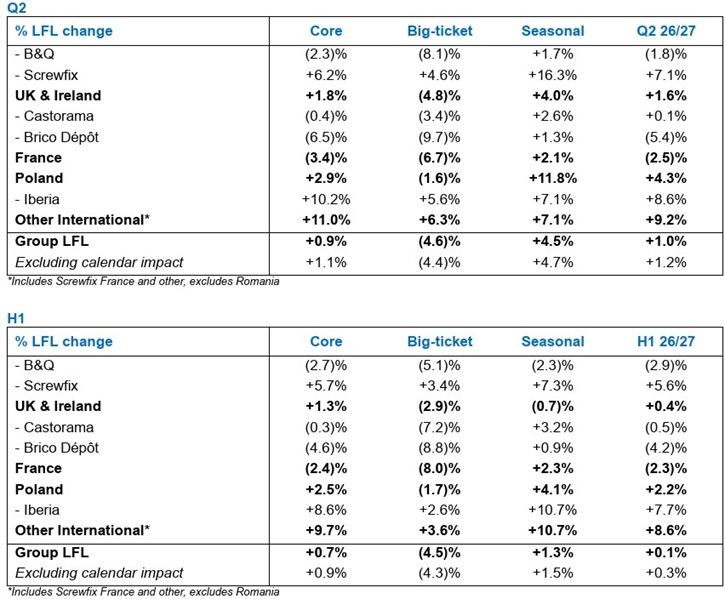 Core* (63% of sales): Resilient performance driven by Screwfix, Poland and Iberia. Growth was broad-based across repair and maintenance work and reflected in tools and hardware, joinery and electrical categories. Core sales were softer at B&Q and Brico Dépôt as heatwaves impacted footfall into stores and delayed larger building projects, tiling and painting.
Big-ticket* (14% of sales): Market outperformance in the kitchen category in the UK and Poland, supported by our new ranges and investment in selling capability. In bathroom, our ranges have underperformed subdued markets. In response, we have launched a comprehensive bathroom range review, with encouraging early results from the launch of Imandra 2, our bathroom furniture range, alongside refreshed sinks and taps ranges.
Seasonal* (23% of sales): Following a strong comparator in Q1, all banners delivered growth in Q2 with heatwaves boosting sales of cooling categories and garden leisure ranges, while impacting categories such as plants, outdoor paint and fencing. We leveraged our OEB capabilities to offer a compelling proposition in cooling and air conditioning. We also benefited from the growing trend towards outdoor living spaces, for example through the launch of our new OEB pergola range.
Market - The home improvement market declined low single digits in H1
B&Q
- Total sales including marketplace GMS (0.1)%, with growth in trade and e-commerce as marketplace continues to scale, offset by soft demand in bathroom. Core LFL impacted by heatwaves driving a shift to online and reducing store footfall
- Market share broadly stable, with share gains in e-commerce and at TradePoint reflecting progress in our strategic growth drivers
- E-commerce sales grew +19%, with penetration reaching 20% (H1 25/26: 16%) and strong performance across 1P and 3P. Marketplace GMV increased +34% to £306m generating retail profit contribution(3) of £12m, supported by range expansion including complementary cooling and electronics products, new cross-border vendors and store click & collect. Continued investment in search and navigation functionality drove improvements in online traffic and conversion rates with the implementation of natural language search planned for H2
- TradePoint sales were resilient with LFL +0.2% and total sales of £490m as TradePoint outperformed the trade market. Penetration now stands at 23% of B&Q sales (H1 25/26: 22%). Growth was driven by active member* growth of +5.3%, expansion of trade sales partners and sales from TSP customers up +23%. E-commerce grew +37%, with our Trade app reaching 49% participation*. We also now offer 3 hour store-to-site delivery, driving incremental sales of construction and trade materials
- Space growth contributed +0.6% to sales with net opening of one new store and the full-year impact of the Homebase stores acquired in the prior year
Screwfix
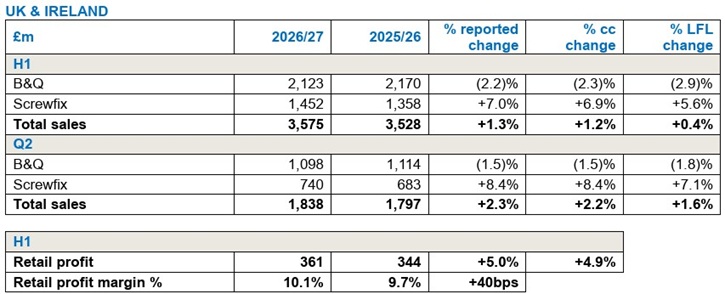
- LFL +5.6% driven by strong volume growth, higher trade customer spend and continued gains in customer acquisition supported by growing app engagement and loyalty programme participation
- Strong market share gains across categories, as Screwfix continues to attract new customers and strengthen its proposition through new loyalty programme features and expanded product ranges both in-store and via vendor fulfilment
- Trade sales +6.1% with penetration at 74%, as Screwfix expanded trade-specific ranges including Hager and Milwaukee. Trade customers are also spending more through the loyalty reward programme
- E-commerce sales +7.5%, with penetration 60% (H1 25/26: 59%). App sales grew +18% and now represent over 42% of e-commerce sales (H1 25/26: 39%). The Screwfix Rewards programme, launched in October 2025, continues to show strong momentum with over +200k new customers enrolled in H1, supported by a new tiered spend & save feature where customers unlock greater savings as they spend. 44% of sales now come from Rewards. Screwfix Sprint, our rapid delivery proposition, grew +50% reflecting the growing demand for rapid fulfilment, particularly in our City stores
- Space growth contributed +1.3% to Screwfix sales with two new store openings, bringing the total of City stores to 39. We are on track to open a total of 16 stores this year UK&I retail profit
- Gross margin increased +50bps, supported by effective product cost management and supplier negotiations, the growing contribution of B&Q's margin-accretive marketplace and retail media, and foreign exchange tailwinds, partly offset by higher freight costs and a higher trade mix
UK&I retail profit
- Gross margin increased +50bps, supported by effective product cost management and supplier negotiations, the growing contribution of B&Q's margin-accretive marketplace and retail media, and foreign exchange tailwinds, partly offset by higher freight costs and a higher trade mix
- Operating costs increased +1.6% driven by two months of increased employer National Insurance contributions, higher wages, more technology investment, new stores, and higher marketing spend linked to phasing. Cost increases were partly offset by savings delivered through B&Q’s prior year operating model changes driving structural cost reductions and a £14m one-off business rates refund
- Retail profit increased +4.9% to £361m (H1 25/26: £344m). Retail profit margin increased +40bps to 10.1%
Source : Kingfisher plc
Image : Kingfisher plc

Insight DIY always publishes the latest news stories before anyone else and we find it to be an invaluable source of customer and market information.

Don't miss out on all the latest, breaking news from the DIY industry