

UK DIY News
Lords: Growth in Merchanting & Digital; Plumbing & Heating Declines
Lords Group Trading plc (AIM: LORD), a leading distributor of building materials, plumbing, heating and DIY products, confirms that amendments to its existing banking facilities, as referenced in the Group’s Interim Results, have now been completed. The Group also provides a trading update for the four months ended 31 October 2026.
Key Highlights
- Banking facility amendments in respect of a revised covenant package completed to meet the Group’s requirements through to March 2029.
- Continued growth in Merchanting and Digital, with both divisions delivering LFL revenue growth in the Period.
- Challenging trading conditions persist in Plumbing & Heating with revenue declining on a LFL basis.
- In context of the current interest rate environment, expectations of a market recovery now delayed until later into FY 2027.
The Group’s Merchanting and Digital divisions have continued to build upon strategic progress made in the first half of the year and both achieved positive LFL revenue in the Period. However, the start to the Plumbing and Heating division winter season has been challenging with trading remaining muted as pressure remains on cost of living and the RMI industry as a whole.
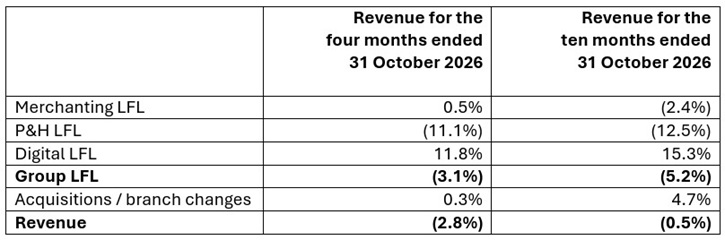
Digital’s continued positive progress in the Period delivered LFL growth of 11.8% through market share gain, despite challenging market conditions.
Merchanting revenue was also ahead of the comparative period and LFL revenue is 2.4% lower in the ten months ended 31 October 2026. The market remained highly competitive, albeit volumes remain subdued and input cost inflation continues to affect the sector. Competitive pressures constrained the ability to pass through supplier price increases in full to customers. Actions to continuously improve efficiency include annualised savings of £1.6 million from restructuring in August 2026, increasing future operational leverage.
LFL revenue in P&H was 11.1% lower in the Period and 12.5% down cumulatively to the end of October 2026. Within the division, the wholesale business, APP, prioritised margin quality over volume, which resulted in lower sales volumes but improved gross margins. As previously announced, the rationalisation of APP’s distribution centres was completed in Q2 of this year. The resultant reduction from seven distribution centres to four is expected to generate c.£1.5 million of annualised cost savings for the division.
Elsewhere, P&H’s spares and trade counter businesses, DH&P and HRP, delivered combined revenue growth of 11.5% during the Period, while renewables revenue more than doubled over the prior period.
Banking Facilities and Liquidity
Further to publication of the Group’s interim results on 30 September 2026, Lords is pleased to announce completion of amendments to the covenant packages in respect of the Group’s existing banking facilities (the ‘Amended Covenants’). The Board appreciates the continued support of its lending banks.
The Amended Covenants are set around quarterly testing thresholds designed to meet the Group’s requirements as it continues to focus on generating cash and strengthening its balance sheet, with reducing Group leverage of 3.0x bank calculated Adjusted EBITDA2 at 31 March 2028 and beyond. The Company has undertaken that no dividends will be paid for so long as Group leverage remains above 3.5x bank calculated Adjusted EBITDA2.
Outlook
While the Group has continued to deliver encouraging progress in Digital and an improving revenue trend in Merchanting, market conditions in P&H have remained more challenging than previously anticipated, particularly at the start of the important winter heating season. As a result, the Board now anticipates that the Group’s Adjusted EBITDA1 for FY 2026 will be approximately £16 million.
In light of current interest rate expectations, the Board now anticipates that a recovery in demand will take longer to emerge than previously assumed, delaying the expected improvement in trading to later in FY 2027.
The Board expects to continue to benefit from operational improvements implemented across the Group, including the annualised cost savings arising from restructuring in Merchanting and P&H. These actions, alongside continued growth in the Group’s specialist businesses, provide a stronger platform for improved profitability at such point that market conditions recover.
The Board remains focused on operational execution, protecting margins, managing costs and cash, and strengthening the Group’s financial position.
Shanker Patel, Chief Executive Officer, commented:
“We are pleased to have completed the amendments to our banking facilities and appreciate the continued support of our lending partners.
“We are encouraged by the performance of Digital, improving LFL revenue in Merchanting, and strong performance in renewables and our spares business DH&P despite market conditions remaining challenging across all our end markets.
“With current interest rate expectations pointing to a slower recovery in demand, we now expect the improvement in trading during FY 2027 to be delayed.
“Our priorities remain improving profitability, generating cash and strengthening the Group’s financial position, while positioning the business to benefit from a recovery in our markets.”
The Insight DIY Perspective
1) Lords' latest update highlights an increasingly important distinction in the building materials sector: businesses with strong digital propositions and specialist customer niches appear better placed to find growth than those more exposed to traditional volume-led distribution. Digital's 11.8% like-for-like growth, alongside continued progress in Merchanting, suggests Lords is making headway in diversifying its revenue streams. However, the scale of the decline in Plumbing & Heating demonstrates how difficult it remains to offset weakness in more established parts of the business.
2) Perhaps the bigger concern is the timing of the recovery. A weaker-than-expected start to the crucial winter heating season, combined with a recovery now pushed back to later in 2027, means Lords must navigate an extended period of subdued demand while managing debt and protecting profitability. The revised banking covenants provide some breathing space, but the suspension of dividends while leverage remains above the agreed threshold underlines the importance of cash generation. The challenge now is to ensure that restructuring and cost savings translate into sustainable performance, rather than simply helping the business weather the downturn.
1 Adjusted EBITDA is earnings before interest, tax, depreciation and amortisation and impairment charges, excluding adjusting items.
2 Bank calculated Adjusted EBITDA excludes IFRS 16 related leases.
Source : Lords Group Trading plc
Image : Lords Group Trading plc


Insight provides a host of information I need on many of our company’s largest customers. I use this information regularly with my team, both at a local level as well as with our other international operations. It’s extremely useful when sharing market intelligence information with our corporate office.

Don't miss out on all the latest, breaking news from the DIY industry