

UK DIY News
Norcros: 'Strong Earnings Growth and Excellent Cash Generation'
Norcros plc (“Norcros” or the “Group”), the UK and Ireland’s number one branded bathroom products business, today announces its interim results for the 26 weeks ended 4 October 2026 (2025: 27 weeks).
Financial summary
Highlights
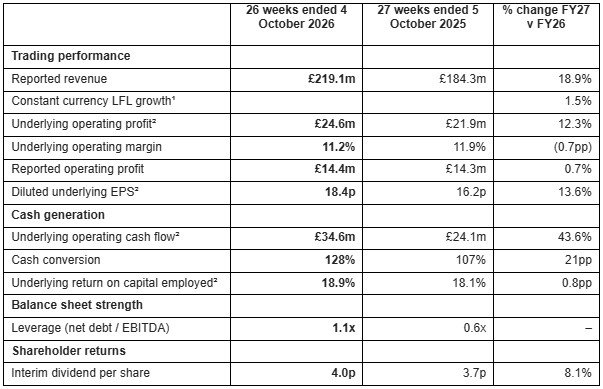
- Revenue up 18.9% to £219.1m, reflecting continued market share gains and contribution from the Fibo acquisition which completed in October 2025
- Record underlying operating profit increased 12.3% to £24.6m
- Diluted underlying EPS increased 13.6% to 18.4p
- Strong cash generation (128% cash conversion), supported by the clearance of manufactured tile stock
- ROCE increased 0.8 percentage points to 18.9%, reflecting a more focused capital-light business
- Leverage reduced to 1.1x underlying EBITDA from 1.6x immediately post the acquisition of Fibo
- Fibo fully integrated and performing well, with the disposal of South Africa progressing to plan
- Strong balance sheet supports our continued organic and inorganic investment to drive growth
- Interim dividend of 4.0p reflecting the strong first half performance
- Full-year underlying operating profit is expected to be in line with market expectations3
Thomas Willcocks, CEO, commented:
“We delivered strong earnings growth of 13.6%, maintained our record of excellent cash generation, and have made meaningful further progress against our strategic targets.
Our individual businesses continue to win market share by staying close to our customers. Strong in-house product development, excellent customer service and increasingly meaningful sustainability credentials are important levers in driving those gains. Our decentralised model gives our teams and businesses that customer and market focus, backed by the scale, capabilities and expertise of the Group.
Fibo is now fully integrated and is performing well, strengthening our position in waterproof wall panels in the UK and Northern Europe and, importantly, providing a platform for further growth in Europe. The potential disposal of our South African operations is progressing as expected. If a sale is achieved, Norcros will have delivered on the strategic objectives first set out two and a half years ago at our Capital Markets Day: to become a European-focused, capital-light branded bathroom products business.
Strong cash generation has reduced leverage to 1.1x underlying EBITDA which gives us the capacity to continue investing in organic growth while also pursuing selective acquisitions that meet our strategic growth and capital allocation criteria. Our approach remains simple: invest, grow, generate cash and reinvest. This approach has allowed the Group to consistently deliver excellent shareholder returns while creating the capacity to continue investing in our existing teams and businesses and pursue selective acquisitions that meet our strategic and financial objectives. This in turn helps lay the foundation for us to continue driving attractive shareholder returns well into the future.
Looking forward, we have successfully implemented our price increases in H1, which will positively impact the second half, and expect to continue growing market share efficiently, drawing on the capabilities our scale provides. Market conditions remain challenging and uncertain, and our focus is on actions within our control. Against this backdrop, our full-year underlying operating profit is expected to be in line with market expectations3.”
OVERVIEW OF RESULTS
Group Financial Summary
The Group delivered a strong performance for the 26 weeks ended 4 October 2026 (2025: 27 weeks), reflecting the strength of our market-leading brands and disciplined execution. Revenue increased 18.9% to £219.1m (2025: £184.3m), including the contribution from Fibo, acquired in October 2025. On a constant currency like-for-like basis, revenue increased 1.5%, with strong growth in South Africa more than offsetting softer European demand in the second quarter.
Underlying operating profit increased 12.3% to £24.6m (2025: £21.9m), and diluted underlying EPS increased 13.6% to 18.4p. The Group’s underlying operating margin was 11.2% (2025: 11.9%), reflecting the dilutive impact of Fibo’s margins in the first half. Cash conversion remained strong at 128%, ROCE increased by 0.8 percentage points to 18.9%, and leverage reduced to 1.1x underlying EBITDA from 1.6x in October 2025, immediately after the Fibo acquisition.
These results continue to demonstrate the strength of our capital-light business model. Our market-leading brands grow through product innovation, cross-selling and excellent customer service, supported by the scale and capabilities of the wider Group. Strong cash generation enables us to reinvest organically and pursue disciplined acquisitions, creating a simple and repeatable model for compounding growth and long-term shareholder returns.
Fibo further illustrates this approach following the successful acquisitions of Merlyn and Grant Westfield: a market-leading, capital-light business with attractive growth and operational leverage opportunities. The acquisition strengthens our position in the UK and Northern Europe and has been successfully integrated and is performing well.
Our leading brands, clear strategic priorities and strong balance sheet leave us well positioned to continue growing the business and make further progress towards our remaining medium-term objectives.
Strategic progress
At our Capital Markets Day in May 2024, we set out our ambition to become a capital-light, sustainable bathroom products business focused primarily on Europe. We have made significant progress over the two and a half years since then, and concluding the potential disposal of our South African operations will complete this transition to a European bathroom products portfolio. Our purpose is to create products and connections that offer sustainable and powerful choices for better living and this guides how we grow Norcros and create long-term value. Our expanding range of sustainable products is earning customer trust and driving commercial growth.
Our strategy is built around four connected pillars: Portfolio Development, Organic Growth, Operational Excellence and ESG. Focused execution through these pillars supports growth, cash generation and improving returns, creating further capacity to invest and grow. Our decentralised model keeps decisions close to customers and markets, while enabling our businesses to benefit from the Group’s capital, scale and capabilities. This combination has underpinned our strategy and our resilience through the cycle and leaves us well positioned to build on our current momentum.
Portfolio Development
During the period, we completed the integration of Fibo, strengthening our position in waterproof wall panels across the UK and Northern Europe, while continuing to advance the planned disposal of our South African operations. Portfolio optimisation and growth remain central to building a more focused, capital-light and cash-generative business of scale. We continue to develop an active acquisition pipeline, including bolt-on opportunities, and remain disciplined in pursuing differentiated, market-leading businesses that meet our strategic and financial criteria and have better than market growth prospects.
Organic Growth
Our businesses grow by taking market share through product innovation, cross-selling and excellent customer service. We continue to actively invest in our new product development programme and Group-wide cross-selling initiatives. Working closely together, Vado and Merlyn gained two further major housebuilder accounts in the period demonstrating our ability to cross-sell. Product vitality remains within our target range of 20% to 25% and with a strong pipeline of launches over the next 12 months. Wall panels continue to take share from tiles, driving growth despite the soft underlying market. Alongside projects across the balance of our portfolio, this gives customers and end consumers an increasingly compelling choice of sustainable bathroom products, and supports profitable market share growth by doing the right thing.
Norcros Europe operating review
Our European businesses delivered a resilient first-half performance in challenging markets. Reported revenue increased 19.6% to £158.9m (2025: £132.9m), reflecting the positive contribution from the Fibo acquisition. Like-for-like revenue was 2.7% lower, with softer UK RMI demand in the second quarter and continued pressure on new build volumes.
In addition to softer underlying demand in Q2, a material operational issue at a key third-party distribution facility affected UK performance. The issue has been resolved and service levels have returned to the standards expected; we do not expect any further impact in H2. Underlying operating profit increased to £21.8m (2025: £19.7m). Operating margin in the region was lower at 13.7% (2025: 14.8%), principally due to the expected dilution caused by the inclusion of Fibo, whose margins are currently lower than the rest of the region.
Fibo
Fibo delivered volume growth in Norway and the UK despite the challenging conditions, as waterproof wall panels continued to take share from traditional tiles. Successfully integrated and performing well, Fibo strengthens our position in this fast-growing category across the UK and Northern Europe. We have invested further in resources to accelerate this growth and make increased use of its available plant capacity. Fibo’s established market position, reputation and management capability in Northern Europe, combined with closer working relationships with our other businesses, provide a meaningful platform for the Group’s further expansion.
Innovation and market share
Product innovation and category expansion continued to support market share gains. Key initiatives included development on Triton’s ENlight with HeatRepeat range and the continued roll out of Croydex’s Metlex brand. We are especially excited by the start of our new Booth & Co traditional bathroom range which is at the early stages of roll out following strong collaboration between Vado and Merlyn.
Cross-selling and collaboration between our businesses created new customer opportunities in both RMI and new build markets driving ongoing market share gains in both market segments. Investment in service, digital capability and supply chain initiatives is supporting this progress. Better forecasting and inventory management are also further strengthening service levels and efficiency, providing a foundation for sustained market share growth and margin progression.
Market conditions remain challenging. RMI accounts for around 80% to 85% of bathroom sector demand, where our branded, non-commoditised products have historically proved more resilient. New-build activity remains subdued, but our leading positions with national and regional housebuilders leave us well placed to benefit from any recovery. Following Iran-linked disruptions, our businesses used the Group’s scale-based supply chain resilience to support customers where possible while evaluating the longer-term impact of the war. Once we had the required clarity and working closely with our customers, we implemented fair and proportionate price increases. These are now in effect, with the benefit more weighted towards H2 than usual. Further margin progress is expected to be supported by increased utilisation of Fibo’s spare capacity as waterproof wall panels continue to gain share from tiles, alongside separate operational improvements across our businesses.
Norcros SA operating review
Our continuing South African businesses delivered a much improved first-half performance despite a challenging economic environment. Revenue was £60.2m (2025: £51.4m), representing constant currency like-for-like growth of 10.9%. Underlying operating profit increased to £2.8m (2025: £2.2m), and operating margin improved to 4.7% (2025: 4.3%).
TAL performed well, supported by targeted new product introductions, operational excellence and strong customer service initiatives, securing new project and customer wins across its core markets. Tile Africa built on the recent momentum with a strong recovery, especially in retail, with better operating disciplines driving market share gains through refreshed product ranges and improved stock availability. House of Plumbing remains challenged by subdued new build residential and large commercial construction activity.
New product development has been an important driver of growth. Tile Africa’s refreshed Evox and Nuvo private label bathroom ranges, together with the continued rollout of the Abode store-within-a-store concept, contributed to improved sales and product vitality metrics. TAL likewise continued to develop its product offering and innovation pipeline. Sustainability initiatives remain embedded across the businesses, including solar energy projects, recycling programmes and more sustainable product solutions.
The planned disposal of our South African operations is progressing to plan and is being managed with our longstanding and experienced team in the region. We are particularly pleased with the focus and commitment shown by our team in South Africa in delivering the strong first-half performance despite the natural uncertainty surrounding the process.
Financial position
Norcros remains in a strong financial position with net debt (pre-IFRS 16) of £55.1m (05 April 2026: £65.8m). Inclusive of IFRS 16 lease liabilities, net debt was £87.0m (05 April 2026: £96.7m). Leverage at the period end was 1.1x underlying EBITDA on a pre-IFRS 16 basis.
Dividend
The Board is declaring an interim dividend of 4.0p per share (H1 2026: 3.7p), an increase of 0.3p (8.1%) per share, reflecting the strong first-half performance and its confidence in the Group’s future prospects. Our capital allocation framework balances investment in organic growth, shareholder returns via our progressive dividend policy and selective acquisitions supported by strong cash generation and disciplined balance sheet management.
The dividend is payable on 12 January 2027 to shareholders on the register on 27 November 2026. The shares will be quoted ex-dividend on 26 November 2026.
The Insight DIY Perspective
Norcros is demonstrating the value of building a portfolio around changing consumer preferences rather than relying solely on market recovery. While like-for-like growth remains relatively modest, its continued market share gains highlight the opportunities available through product innovation, cross-selling and category development. The growing popularity of waterproof wall panels at the expense of traditional tiles is particularly interesting, with Fibo giving the Group an increasingly important position in a category that offers further growth potential. This also reinforces the importance of having a differentiated product proposition in a subdued bathroom market.
The next challenge is converting its enlarged portfolio into stronger organic growth and improved margins. The Fibo acquisition has added scale and strategic capability, but has also diluted operating margins, while softer European demand underlines the difficulties facing the wider bathroom sector. The planned South African disposal would further sharpen Norcros's European focus, potentially creating additional capacity for investment and acquisitions. In the meantime, the benefit of recently implemented price increases and greater utilisation of Fibo's manufacturing capacity should provide opportunities to improve profitability. The strategy is progressing, but the ability to deliver growth without continued reliance on acquisitions will be an important measure of its longer-term success.
1 LFL (like-for-like) adjusting prior year from a 27 to 26 week period pro-rating and adjusting for Fibo which was acquired in the second half of the prior year
2 Definitions and reconciliations of alternative performance measures are provided in note 3
3 Norcros compiled analyst consensus range for underlying operating profit for the year to 4 April 2027, as at 19 November 2026, is £53.0m to £54.7m
Source : Norcros plc
Image : Norcros plc


Insight DIY always publishes the latest news stories before anyone else and we find it to be an invaluable source of customer and market information.

Don't miss out on all the latest, breaking news from the DIY industry